Thursday, April 25, 2013

Modified mortgages show ‘alarming’ default trend


Troubled homeowners who received modified mortgages through a federal program are seeing high default rates, a troubling trend that officials inadequately understand, according to an investigator’s report released Wednesday.
The oldest permanent modifications made through the federal Home Affordable Modification Program, which launched in 2009, were redefaulting at a rate of 46.1% as of March 31, according to the report from the special inspector general overseeing the Treasury Department’s efforts to shore up the U.S. financial system. HAMP’s permanent modifications from 2010 have redefault rates ranging from 28.9% to 37.6%.
“The number of homeowners who have redefaulted on a HAMP permanent mortgage modification is increasing at an alarming rate,” the report said. “Treasury’s data shows that the longer a homeowner remains in HAMP, the more likely he or she is to redefault out of the program.”
Unfortunately, Treasury officials have an insufficient understanding of factors behind failures, according to the report.
“Better knowledge of the characteristics of the loan, the homeowners, the servicer, or the modification, more prone to redefault will increase Treasury’s understanding of the underlying problems that cause redefaults and provide Treasury an opportunity to address these issues proactively,” the inspector general said.
HAMP mortgages are modified to lower monthly payments by cutting interest rates and extending terms, among other actions. Servicers and borrowers receive incentive payments through the program.
Unsuccessful modifications have a “devastating effect,” according to the report.
“Redefaulted HAMP modifications on already struggling homeowners when any amounts previously modified suddenly come due,” according to the report. “When the homeowner cannot pay it, they lose their home to foreclosure.”
When Treasury launched HAMP, officials said the program could help 3 million to 4 million at-risk homeowners avoid foreclosure. However, as of March 31, only about 2 million HAMP modifications had been started, and 54% of these have been cancelled, according to the report.
Looking at Treasury’s use of funds from the Troubled Asset Relief Program, which was designed to shore up the U.S. financial system, less than 2%, or about $7.3 billion, has been spent on homeowner-relief programs, such as HAMP, as of March 31. Meanwhile, Treasury has spent 75% of TARP funds on rescuing financial institutions, the report said.
“For example, the PNC Financial Services Group PNC +1.24%, a large regional east coast bank, alone received $7.6 billion, nearly the same amount of TARP funds used to help struggling homeowners throughout the nation,” according to the report. “Treasury pulled out all the stops for the largest financial institutions, and it must do the same for homeowners.”
–Ruth Mantell

Wednesday, April 24, 2013

ERIC SCHNEIDERMAN CHALLENGES OBAMA ADMINISTRATION OVER MORTGAGE INVESTIGATIONS


WASHINGTON -- New York Attorney General Eric Schneiderman has privately criticized the Obama administration and the Department of Justice for not aggressively investigating dodgy mortgage deals that helped trigger the financial crisis, according to senators and congressional aides who met with him this month.
New York’s top prosecutor is co-chair of the administration’s year-old Residential Mortgage Backed Securities Working Group, an initiative that President Barack Obama called for in his State of the Union address last year. In a sign of Schneiderman’s importance to the group, the White House seated him behind Michelle Obama during the speech.
Schneiderman, a Democrat who has attempted to investigate Wall Street, expressed his frustrations with the administration earlier this month during private meetings with Democratic senators on Capitol Hill, arguing that he was “naive” when he first entered into the partnership with the Justice Department, lawmakers and their aides said.
Critics of Schneiderman's collaboration, which came in exchange for his assent to a national mortgage settlement, warned at the time that the attorney general was being played. His recent criticisms of the administration may renew allegations that he, too, has compiled a lackluster enforcement record.
Schneiderman has recently directed his attention to working with lawmakers and outside groups to pressure the administration to toughen its approach. He traveled to Washington for meetings with Sens. Elizabeth Warren (D-Mass.), Carl Levin (D-Mich.), Sherrod Brown (D-Ohio) and Jeff Merkley (D-Ore.), among others, according to people who attended the meetings. The four senators have been among the loudest critics of the Obama administration's efforts to hold the financial industry accountable for alleged wrongdoing, charging they have not gone far enough.
Examples of criticized settlements include the Justice Department's decision not to file criminal charges against financial companies accused of manipulating benchmark interest rates, as well as banks alleged to have helped drug cartels launder money through the U.S. financial system. Government panels like the Financial Crisis Inquiry Commission and the Levin-chaired Permanent Subcommittee on Investigations that referred cases for potential prosecution have seen their recommendations cast aside.
Schneiderman excoriated Justice Department officials for their approach in targeting wrongdoing by financial institutions in private meetings with lawmakers.
“He expressed similar frustrations that the public has expressed,” Levin said.
Levin said that Schneiderman argued that the Justice Department lacks the “political will” to forge ahead with prosecutions of high-ranking financial executives and large financial groups.
“There's been a real lack of going after the top folks, in general,” Levin said. His subcommittee has aggressively probed potential wrongdoing by leading financial institutions, including alleged money laundering at HSBC and mortgage-related misdeeds at Goldman Sachs.
Another senator, who requested anonymity, said of Schneiderman that it's “very clear he's extremely frustrated."
Schneiderman’s behind-the-scenes criticism may sting administration and enforcement officials, who for years have been dogged by allegations that they have been soft on Wall Street.
The White House attempted to rebut those accusations in part by giving Schneiderman a plum role on a unit launched with great fanfare. He was promised aggressive prosecutors and investigators who through enforcement action would put to rest allegations that the Obama administration has been lax on pre-financial crisis misconduct.
The Justice Department has promoted four cases as having been brought thanks to the securitization task force: two separate settlements reached between the Securities and Exchange Commission and JPMorgan Chase and Credit Suisse, and two civil cases Schneiderman has brought in state court against those same banks.
The SEC’s settlements ended investigations that began long before the formation of the securitization task force.
Critics allege the task force has racked up an unimpressive record. In a sign of its decreased standing at the White House, Obama did not mention it in his State of the Union address earlier this year.
“No one is happy with the pace of the task force at all. It's a travesty,” said Brian Kettenring, a community organizer who runs the advocacy groups Leadership Center for the Common Good and Campaign for a Fair Settlement. “It’s one of the biggest black marks on this administration, in terms of what they promised versus what has happened.”
Michael Bresnick, executive director of the Obama-formed Financial Fraud Enforcement Task Force, an oft-criticized collection of regulators that has spent much of its time targeting low-level mortgage brokers and borrowers, said last month the RMBS group is “actively investigating fraud” related to mortgage securities.
More than 200 people from the working group are currently investigating potential misconduct in mortgage securities, the Justice Department said.
“Many more investigations are ongoing,” Bresnick said.
Part of the administration’s embrace of Schneiderman was guided by his appeal to liberal groups, who view him as the new sheriff of Wall Street and have criticized the administration’s approach to alleged misconduct by big banks.
Schneiderman often describes how he is holding Wall Street accountable during private meetings with key interest groups, participants in the meetings have said. His office has demanded various internal bank documents on activity ranging from alleged attempts to manipulate benchmark interest rates to the pre-financial crisis securitizations of home loans that eventually defaulted.
New York’s top law enforcement officer also has the two pending civil cases against Credit Suisse and JPMorgan Chase for allegedly misleading investors in mortgage bonds. Both banks have disputed the allegations.
Schneiderman relied on the Justice Department to bring those two cases, officials said. The agency and several U.S. Attorney’s Offices combined to interview more than 40 people and provided more than a dozen analysts and attorneys to review documents for Schneiderman’s lawsuits, officials said.
“The sharing of information and expertise has been certainly beyond anything I've ever seen or been aware of," Schneiderman said when he announced his JPMorgan lawsuit in October. "It has enabled us to move forward more quickly and more aggressively than we would have.”
Justice spokeswoman Adora Andy Jenkins said the agency “supplied and continues to supply crucial investigative and litigation support, technological resources, and expertise to these cases.”
In the months after Schneiderman took office in 2011, large financial institutions and their lawyers said they feared him. Now, some have said privately in interviews that they view him as a nuisance, given the dearth of cases he has brought in light of his aggressive requests for documents.
Instead, another New York state regulator who is viewed as a rival, Superintendent of Financial Services Benjamin Lawsky, has emerged as the key Wall Street scourge, earning the enmity of some industry executives for his enforcement activities and willingness to buck federal regulators.
In his most notable case, Lawsky secured $340 million from Standard Chartered, a UK bank, to settle accusations the bank hid key details from regulators involving at least $250 billion in illicit transactions with Iran and potentially violated U.S. sanctions policy.
At the time of the settlement, Levin, the powerful chairman of the Senate's investigations panel, said that Lawsky and his team "showed that holding a bank accountable for past misconduct doesn’t need to take years of negotiation over the size of the penalty; it simply requires a regulator with backbone to act.”
Members of advocacy groups who have met with Schneiderman have expressed disappointment in his own efforts to hold financial institutions accountable, and question his criticisms of the administration. Those who spoke on the condition of anonymity for fear of jeopardizing their relationships with his office described Schneiderman’s rhetoric as far more aggressive than his investigations.
"Millions of households are still reeling from the mortgage crisis, which continues to be a drag on our economic recovery," said Schneiderman spokesman Damien LaVera in response.
“The attorney general ... is working constructively with the Justice Department ... [and] will continue to work on multiple fronts with activists and allies inside and outside the government to find aggressive, creative ways to ensure that struggling homeowners in New York and around the country get the relief they deserve,” LaVera added.
Schneiderman maintains the backing of some liberal groups, in part because of his efforts to convince the White House to fire Edward DeMarco, the government regulator overseeing state-controlled mortgage giants Fannie Mae and Freddie Mac.
Some of these groups have been critical of DeMarco, the acting head of the Federal Housing Finance Agency, for his refusal to allow the mortgage companies to forgive distressed borrowers’ mortgage debt. Earlier this year Schneiderman prepared a memo outlining a potential way in which the White House could replace DeMarco.

Thursday, April 18, 2013

NY settles QBE force-placed insurance case for $10 million


The New York State Department of Financial Services settled an investigation into the force-placed insurance practices ofQBE for $10 million, according to the offices of Governor Andrew Cuomo.
QBE will pay that multi-million penalty while also compensating homeowners harmed by QBE’s force-placed insurance practices. The company also agreed to undergo a series of reforms.
Force-placed insurance is the practice of a servicer or bank taking out an insurance policy when a homeowners own insurance policy lapses.
Controversies have developed from the practice with the policies placed on the properties often more expensive than voluntary insurance contracts.
New York Superintendent of Financial Services Benjamin Lawsky said in a statement, "QBE has done the right thing by adopting these reforms.  We now need to ensure that the entire industry in New York – 100% of it – is subject to our reforms."
The state’s settlement with QBE follows a deal New York struck with Assurant over the same type of practices. With QBE now settling, Cuomo says the deal resolves issues at two firms responsible for 90% of the force-placed insurance market in New York.
In the case of QBE, New York investigators claim QBE paid commissions to insurance agencies and brokers affiliated with mortgage servicers to secure their business.
In other words, rather than competing in the market by offering lower premiums for insurance, New York regulators claim QBE competed for banks and servicers' insurance business by offering them a share in the profits.

This meant higher premiums for homeowners and potentially more losses born by taxpayers if the loans in question were owned or backed by Fannie Mae and Freddie Mac.
"Typically, the commissions are ten to twenty percent of the premium written on the servicer’s mortgage loan portfolio," Cuomo’s office said. But, he said, "the evidence from the investigation indicates that the affiliated agencies and brokers do little or no work for the commissions QBE had paid them."
New York authorities also pointed out apparent conflicts of interest.
Back in 2011, QBE bought Balboa Insurance Co., the force-placed insurance business of Bank of America. Balboa previously provided force-placed insurance on Countrywide and BOA-serviced mortgages, which are owned in large part by investors, Cuomo said.
The arrangement was profitable for Countrywide and BOA. However, the New York Governor says it also "created a potential conflict of interest insofar as Countrywide’s and BOA’s bottom line could improve as their Balboa subsidiaries force placed more policies."
For the Full Article Click Here: www.housingwire.com

Monday, April 15, 2013

As NY foreclosures soar, DC blocks probe


Foreclosures are rising dramatically in New York City — even as federal regulators are waging a fight to protect big banks from regulatory scrutiny of illegal foreclosure activity.
Nationwide, foreclosure filings dropped 23 percent in March compared with the year-ago period.
In New York City, by contrast, filings vaulted by 150 percent, which is the biggest percentage increase in 12 months, according to the foreclosure-information firm RealtyTrac.
“The trend is not only continuing but accelerating,” said Daren Blomquist, vice president of RealtyTrac.
Manhattan remains largely immune to foreclosure pain, but Queens, Brooklyn and Staten Island are taking it on the chin.
Foreclosures have been rising for six months straight in Brooklyn and 11 months in a row in Queens. Staten Island continues to have the highest foreclosure rate in the state, with 1 out of every 350 housing units in foreclosure.
Legal-services attorneys say more middle-class New Yorkers are facing foreclosure. Squeezed by high housing costs and low wages, families cannot save to weather a job loss or medical crisis.
New York’s foreclosure uptick comes amid news last week that the Federal Reserve and Office of the Comptroller of the Currency refused a congressional request to turn over documents that were related to illegal foreclosures by mortgage servicers.
The excuse that was offered by Federal Reserve Chairman Ben Bernanke and Comptroller of the Currency Thomas Curry is that these documents come under the category of trade secrets.
“It is incomprehensible that federal regulators would claim that illegal bank actions — which they uncovered — are corporate trade secrets that must be withheld from Congress,” Rep. Elijah Cummings (D-Md.) told The Post.
Despite this setback, Cummings and Sen. Elizabeth Warren (D-Mass.) are pressing ahead with their requests, which were begun in January after the OCC abruptly shut down its review of the national foreclosure settlement.
Congress has the power to subpoena the Fed and OCC for the documents.
At a Senate hearing last Thursday, Warren said, “People want to know that their regulators are watching out for the American public, not for the banks.”

Friday, April 12, 2013

Free mediation sessions offered to Staten Island storm victims battling with insurers


STATEN ISLAND, N.Y. -- The New York State Department of Financial Services has hired the American Arbitration Association to host mediation sessions between insurance companies and storm victims -- and 841 Staten Islanders who still have open claims for damage to real or personal property qualify for the assistance.

"It's voluntary. It's non-binding, it's non-adversarial, unlike arbitration or litigation," Jeffrey T. Zaino, vice president of the association, said at a Borough Hall press conference Wednesday.

And it's free -- insurance companies will be footing the bill.

The mediation sessions are open to people whose claims for loss or damage to real or personal property were denied, in either part or in whole, or who haven't been offered a settlement within 45 days of submitting their documents. Flood insurance claims do not qualify.

Zaino said many of those more than 800 open claims will be resolved before going to mediation, but for others, it will be a good option. So far, just 15 Staten Islanders have registered for mediation, and the first one will be held tomorrow. 

The two-hour process sees the insured and the insurance company sitting in a room with one of AAA's mediators -- all of whom will have more than five years' experience and 35 hours' training.

After a person accepts a settlement from her insurance company, she has three days to change her mind, Zaino said.

Citywide, there are about 15,000 claims still unsettled.
"We think mediation is the solution," Zaino said.

Borough President James Molinaro praised the program, saying Gov. Andrew Cuomo and others recognized insurance difficulties have been a prime concern since the storm.
"There was one complaint almost every family I spoke to gave me, and that was with the insurance companies," Molinaro said.

AAA needed a place to set up shop on Staten Island, so Molinaro reached out to Frank Siller of the Stephen Siller Tunnel to the Towers Foundation, who offered up space in their Hylan Boulevard office, where storm victims regularly visit for other types of help.

"So many people don't know the answers with their insurance companies, and I think Jeff is going to resolve that," Siller said.

To register for the program, visit adr.org, e-mail stormsandyny@adr.org, or call 855-366-9767. 

Applicants must complete a two-page form.

Thursday, April 11, 2013

FED ARGUES THAT MORTGAGE ABUSES ARE TRADE SECRETS, MEANING INSTITUTIONALIZED FRAUD


When the media discusses how banks have ridden like a steamroller over borrowers and investors, the typical response is a combination of minimization and distancing: that the offense wasn’t such a big deal and that it was a mistake. Recall the PR barrage in the wake of the robosigning scandal: its was “sloppiness,” “paperwork errors”. Servicers kept claiming, despite overwhelming evidence of bad faith and the institutionalization of impermissible practices, that there was really nothing wrong with how they were operating. Remember it was important for them to take that position, because if they were to admit that the bank knew it was engaging in widespread abuses with management knowledge and approval, it would be admitting to fraud.
Two major government settlements later, this position is looking awfully strained. And the Fed, in stonewalling Elizabeth Warren’s and Elijah Cumming’s efforts to get more information about the Independent Foreclosure Reviews, presented the bad practices as servicer policies, which means that they were deliberate, hence, fraudulent.
By way of background: Warren and Cummings have been asking the OCC and Fed for some time for more information about what happened in the foreclosure reviews. Out of fourteen information requests they made in a January letter, they got only one question answered in full, and mere partial responses to three other questions. They requested, and got, a meeting yesterday. They issued a letter Wednesday that described what transpired. Key sections:
Two years ago this week, your offices issued a public report announcing that you determined that 14 mortgage servicing companies were engaging in “violations of applicable federal and state law.” You found that these abuses have “widespread consequences for the national housing market and borrowers.” You also explicitly referenced instances of abuse, including illegal foreclosures against our nation’s men and women in uniform who are protected by the Servicemembers Civil Relief Act (SCRA)….
We have requested information about the process used to conduct this review and the extent to which violations of law were found….
At the meeting yesterday, Federal Reserve staff argued that the documents relating to widespread legal violations are the “trade secrets” of mortgage servicing companies. In addition, staff from the Office of the Comptroller of the Currency (OCC) argued that these documents should be withheld from Members of Congress because producing them could be interpreted as a waiver of their authority to prevent disclosure to the public of confidential supervisory bank examination information.
Now since the Fed is apparently making this absurd argument in all seriousness, let’s look at the implications. A trade secret is a form of intellectual property. I encourage IP experts to pipe up in comments, but my understanding, based on the experience of a client who successfully sued a former employee for violating trade secrets, is that it is difficult to prove that your internal know-how rises to the level of being a trade secret. One of the key elements in making the case is that you have to show you went to some length to keep your special tricks secret, such as limiting access to them, having employees sign confidentiality agreements, etc.
Why does this matter? You can’t have internal knowledge rise to the level of being a trade secret unless their was an institutional decision to keep it secret. That means the Fed is effectively saying that servicer management, and almost certainly bank management (since servicing units don’t have their own corporate counsel) was fully aware of the nature of the practices at issue and chose to keep them secret, supposedly for competitive reasons. This is fact is one of the things lawyers have been eager to establish, namely that bank management knew full well all these servicing tricks were happening, and sought to protect them as important sources of profit. Way to go, Fed!
Now, of course, this argument is revealing in a lot of other ways. The Fed has also just admitted it thinks it is more important to protect bank knowledge of how to break the law than expose the information. So the Fed has also made explicit that it wants to preserve banks’ ability to rip off people. So the Fed’s official policy is bank profits trump the law. Not that we didn’t know that, but it has now been stated in a baldfaced manner.
The OCC’s position, that they need to preserve confidential bank examination information, is equally ridiculous (the letter gives a long-form debunking). Warren and Cummings noted,
You may protect against such a waiver by including standard language in a cover letter explaining that providing documents to Members of Congress, even if normally not disclosed to the public because of their proprietary or confidential nature, does not constitute a waiver.
But it’s doubtful that the information at hand is “bank examination information”. The reason for keeping bank examination results confidential is to prevent bank runs. Mortgage servicing units are not banks. In fact, the OCC said repeatedly when it was pilloried for its failure to supervise servciers that didn’t have much in the way of formal authority over them. It wasn’t acting as a bank examiner of servicing units for the period that was the focus of the IFR, 2009 and 2010. Given the poor control over information during the IFR (for instance, at Bank of America, the army of temps who performed the project didn’t sign enforceable confidentiality agreements), and the fact that lots of relevant information (investor reports, court documents, including the affidavits used for the fraudulent fees) are public records, the OCC argument isn’t credible. It becomes even more of a howler when you look at the questions that the OCC and Fed are refusing to answer. Tell me how bank operations might be harmed by answering this question, for instance:
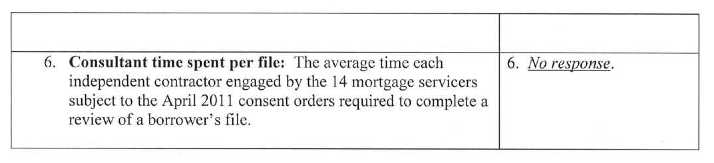
Screen shot 2013-04-11 at 3.26.09 AM
And why are the Fed and the OCC fighting Warren and Cummings so hard? It’s not as if the information they seek would help an individual borrower in litigation against a bank, except in a very general way. For instance, Warren and Cummings ask for the number of borrower files in which unsafe or unsound practices were found. If it was revealed that Bank of America had a high proportion of files with errors, as our whistleblowers found, that might persuade a judge that a borrower case not be thrown out in summary judgment.
But the real exposure of the banks is to investor litigation. The Bank of America sources who did fee reviews found virtually all their files had errors (their reflex was to say all files had errors, but most would then correct themselves and say 90% or 95% since they could not be sure someone didn’t get a batch of files that were fine). In many cases, the errors weren’t large enough to have caused a borrower to lose his house. But remember, if a home is foreclosed on, all fees (late fees, attorney fees, property inspection charges) are reimbursed first, so excessive frequency or size of foreclosure-related fees is a transfer from investors to servicers. So if the OCC and Fed were to confirm that there were large-scale abuses, investors might saddle up to go after the servicers.
This exchange also confirms something the public knows all too well: the regulators are in the business of protecting the banks, and only secondarily in enforcing the law. And until that changes, it is the safety and soundness of the population that is at risk.

Read more at http://www.nakedcapitalism.com/2013/04/fed-argues-that-mortgage-abuses-are-trade-secrets-meaning-institutionalized-fraud.html#PqEECWc8aLaHacAW.99 

Wednesday, April 10, 2013

Staten Island Event to Honor Ciparick, Raise Sandy Funds


Staten Island Legal Services will host a luncheon on April 19 to honor former Court of Appeals Judge Carmen Beauchamp Ciparick and to raise funds for the group's Hurricane Sandy legal support efforts. Former Governor Mario Cuomo will present Ciparick with Staten Island Legal Services' first annual Vito J. Titone Award for Legal Excellence, named for the Court of Appeals judge who died in 2005. Ciparick, who retired on Dec. 31 after 35 years on the bench, more than 18 on the Court of Appeals, is now of counsel to Greenberg Traurig.
Staten Island Legal Services has helped more than 400 people since the Oct. 29 storm and has 200 open cases, most involving FEMA and insurance issues. "When the storm hit, we were already taxed to capacity and suddenly we were tackling an area we had no experience in," said Nancy Goldhill, the group's director. "It's been extremely difficult." The group has raised funds to hire three additional attorneys to form a disaster recovery unit, which now has a full caseload. Sandy-related legal issues could take several years to resolve, said Goldhill, who added that the group is seeking additional funds to increase storm-related resources and maintain services in foreclosure prevention, family law, immigration and financial counseling.
The April 19 event will be held from noon to 2 p.m. at the Staten Island Hilton Garden Inn, 1100 South Ave. To RSVP or buy tickets, contact Clara Saviñon at 718-233-6494 or csavinon@silsnyc.org.

Supreme Court Upholds Ability of Successful Fair Debt Collection Practices Act (FDCPA) Defendant to Recover Costs


Article By:Michael B. Watkins


In a 7-2 decision, the United States Supreme Court ruled in the case of Marx v. General Revenue Corp. that a provision of the Fair Debt Collection Practices Act (the FDCPA), namely 15 U.S.C. §1692k(a)(3) does not prohibit a court pursuant to a potentially conflicting or superseding provision of the Federal Rule of Civil Procedure from otherwise awarding costs to the defendant as the prevailing party in the litigation.
The facts of this case show that General Revenue Corp. (GRC) was hired to collect on a defaulted student loan by Marx. In response to the collection activity, Marx filed suit against GRC alleging that it violated the FDCPA by making harassing phone calls, threatening to garnish an improper percentage of her wages and wrongfully sending correspondence to her employer requesting information on her employment status. The District Court ruled in favor of GRC following a bench trial, finding no violation of the FDCPA. Afterward, GRC submitted a bill of costs for witness fees, witness travel expenses and deposition transcript fees totaling $7,779.16 pursuant to FRCP 54(d)(1). The District Court disallowed certain items but entered an award of $4,543.03 in favor of GRC. Marx sought to vacate the District Court's award on the basis that the FDCPA provides, in essence, the exclusive basis for an award of costs under FDCPA based actions but that this controlling statute did not apply to these facts.
The purportedly controlling statute, 15 U.S.C. §1692k(a)(3) provides that if a plaintiff's action under the FDCPA "was brought in bad faith and for the purpose of harassment, the court may award to the defendant attorneys' fees reasonable in relation to the work expended and costs". FRCP 54(d)(i), on the other hand, states that "[u]nless a federal statute¼ provides otherwis e, costs - other than attorneys' fees - should be allowed to the prevailing party" (emphasis supplied). Marx argued to the District Court that since she was not found to have asserted her claim in bad faith or for purposes of harassment, then 15 U.S.C. §1692k(a)(3) is a federal statute which does "provide otherwise" and thus displaces the ability of a court to award costs pursuant to FRCP 54(d)(i). Neither the District Court, the 10th Circuit Court of Appeals, nor the United States Supreme Court agreed with Marx's analysis.
The crux of Marx's argument, as the Supreme Court saw it, was that a court's discretion under FRCP 54(d)(1) to award costs was displaced by negative implication under §1692k(a)(3). In other words, since the statute speaks to an award of costs where both bad faith and harassing conduct exist, then an award of costs is unavailable absent such conduct. The Court rejected this argument, however, as an attempt to read too much into congressional intent, determining that the context instead indicated Congress's intent that the statute did not foreclose an award of cost under the Rule, even in the absence of bad faith and harassment in Marx's pursuit of the FDCPA action.
Although a court's discretion remains limited in awarding attorneys' fees to the prevailing party to the "American Rule" (each party pays their own fees) except in instances of bad faith and harassing conduct in FDCPA cases, it is now uniformly established that a court has the discretion to award costs to the prevailing party defendant irrespective of the plaintiff's motive or conduct in bringing the action. Because costs can in and of themselves represent a significant outlay, this decision may serve to cause FDCPA plaintiffs to think twice before bringing an FDCPA action if the facts are not clearly in their favor.
© 2013 BARNES & THORNBURG LLP

Tuesday, April 9, 2013

The Rise and Fall of Foreclosure Mills...

"Outstanding Law Review article analyzing the rise and fall of foreclosure mills."
-Robert E. Brown, Esq


Friday, March 29, 2013

Purported Non-Compliance with Requirements of Administrative Order 548/10 Insufficient to Vacate Judgment of Foreclosure and Sale


By Matthew D. Donovan on March 19th, 2013
Posted in Administrative Order 548/10, CPLR 3408, CPLR 5015

In a February 19, 2013, decision by Justice Whelan, the court denied plaintiff-mortgagee-lender’s motion to vacate a judgment of foreclosure and sale, as well as the order of reference, and to extend the notice of pendency. Plaintiff moved on the basis of an alleged failure by a prior servicer to comply with the new substantive requirements of Administrative Order 548/10 (the “Admin. Order”). The underlying foreclosure action was commenced in January 2008. Defendant-mortgagor-borrower failed to answer and appear. A judgment of foreclosure and sale was granted in July 2010, which noted that defendant was in default for an amount in excess of $350,000. The court began its analysis of plaintiff’s motion by reiterating its previous finding that the Admin. Order and its additional substantive requirements “constitute[d] an impermissible exercise of the rule making authority vested in the chief administrator of the courts” and therefore was “an unauthorized intrusion upon the jural relations of the parties to this action and upon the court.” The court then found that, in any event, the attorney affirmation and the servicer affidavit submitted by the prior servicer were in compliance with the requirements of the Admin. Order. Noting that the foreclosure action had been pending for over 1,800 days, the court concluded that “[t]he time had come” for an end to the litigation.

US Bank v Castillo, Sup Ct, Suffolk County, January 19, 2013, Whelan, J., Index No. 2161/08


"The courts are really starting to swing back in favor of the banks and are increasingly showing  “the time had come for an end to the litigation” mindset." -Robert E. Brown, Esq.

Monday, March 25, 2013

ResCap Told to Seek New Foreclosure-Review Deal With U.S.


Residential Capital LLC should try to negotiate a new foreclosure-review process with federal regulators before seeking a bankruptcy court order to halt the $300 million program, a judge said.
U.S. Bankruptcy Judge Martin Glenn in Manhattan told ResCap today he wouldn’t rule immediately on the company’s request to suspend its obligation to find any damages suffered by borrowers who went through foreclosure. ResCap, through its GMAC Mortgage unit, agreed to the review under a settlement with U.S. regulators before filing for bankruptcy last year.
The review, which may cost about $300 million, is a waste of money because a new federal policy allows a lump-sum payment to be split among borrowers, a lawyer for ResCap said today. That would be cheaper than paying PricewaterhouseCoopers LLP to conduct the review, the company said.
“You have to negotiate with the Fed and then come back to me,” Glenn said, referring to the U.S. Federal Reserve, which is requiring the review. “I’m not ruling today, I’m making that crystal clear.”
The review may yield $35 million to $60 million to homeowners who have been harmed, the official committee of ResCap creditors said in court papers.
The company has asked Glenn to declare that costs of paying damages found by the review are unsecured claims, which would give them a lower repayment priority than other company debts.
ResCap, based in New York, filed for bankruptcy in May with plans to sell most of its assets and resolve legal claims related to residential mortgage-backed securities.
Last year, in what the U.S. called the largest federal- state civil settlement its history, the nation’s five largest mortgage servicers committed $20 billion in relief for borrowers plus payments of $5 billion to governments.
The case is In re Residential Capital LLC, 12-12020, U.S. Bankruptcy Court, Southern District of New York (Manhattan).

Friday, March 8, 2013

DECISION: U.S. National Association v. Said

Summary Judgement was granted in favor of the homeowner where the Court determined the bank lacked standing due to a defective MERS assignment.


Thursday, March 7, 2013

Mortgage Buyer Lacks Personal Knowledge of Default; Judge Blocks Foreclosure Bid


Mortgage Buyer Lacks Personal Knowledge of Default; Judge Blocks Foreclosure Bid
Brendan Pierson
New York Law Journal


The buyer of a mortgage that is already in default cannot foreclose on the mortgage because it does not have personal knowledge of the default, a state judge has ruled, though the buyer may be able to remedy that if it can get an affidavit from the mortgage's previous owner.
In a Feb. 14 order in FTBK Investor II v. Joshua Management, 810164/11, Manhattan Supreme Court Justice Paul Wooten also rejected several other arguments put forward by the mortgage borrower attempting to avoid default.

The defendant in the case, Joshua Management, originally took out a mortgage from Washington Mutual to buy a property at 2866 Frederick Douglass Blvd. in Harlem in 2005. In 2008, Washington Mutual was seized by the federal Office of Thrift Supervision and then put in control of the Federal Deposit Insurance Corp. It was subsequently sold to JPMorgan Chase & Co.

In May 2011, Chase began a foreclosure action against Joshua, alleging it had stopped making mortgage payments in December 2010. In fall 2011, the mortgage was transferred to a company called NY Brooklyn Investor and then to FTBK Investor II. FTBK took the place of Chase in the foreclosure action and moved for summary judgment.

Joshua opposed, arguing that FTBK had not shown that the mortgage was ever transferred from Washington Mutual to Chase. Joshua acknowledged that FTBK is in physical possession of the mortgage document, but said that it had to provide a record that the document was delivered from Washington Mutual to Chase.
0.

Furthermore, Joshua argued that because the alleged default happened before FTBK acquired the mortgage, FTBK could not foreclose on it because it lacked personal knowledge of the default.
Wooten rejected Joshua's first argument, finding that FTBK does not have to show that the mortgage was individually transferred from Washington Mutual to Chase because federal law gives the Office of Thrift Supervision and the FDIC the power to transfer Washington Mutual's assets without individual assignments….
*       *       *
However, he did accept Joshua's second argument, that FTBK did not have personal knowledge of the default….
______________________________________
FTBK Investor Ii LLC v. Joshua Management LLC, 810164/11
Supreme Court, New York County, Part 7
810164/11
New York Law Journal
03-07-2013
Cite as: FTBK Investor Ii LLC v. Joshua Management LLC, 810164/11, NYLJ 1202590547576, at *1 (Sup., NY, Decided February 2013)
Justice Paul Wooten
Decided: February 2013

Additional Defendants
New York State Department of Taxation and Finance, New York City Department of Finance, New York City Environmental Control Board, Castle Oil Corp., New York City Department of Housing Preservation and Development, and "John Doe No. I" to "John Doe No. Xxx," Inclusive, the Last Thirty Names Being Fictitious and Unknown to Plaintiff, the Persons or Parties Intended Being the Tenants, Occupants, Persons or Corporations, If, any, Having or Claiming an Interest In or Lien Upon the Premises Described In the Complaint
*1
Motion sequences 003 and 004 are hereby consolidated for purposes of disposition. In this action, FTBK Investor II, LLC, as Trustee for N.Y. Brooklyn Investor II Trust 1 (plaintiff) seeks to foreclose upon a mortgage secured by property located at 2866 Frederick Douglas Boulevard, New York, New York and owned by defendant Joshua Management, LLC (Joshua). The mortgage agreement and an Amended and Restated Promissory Note (Note) in the amount of $2,812,500.00 were originally executed by Joshua in favor of Washington Mutual Bank, F.A.
*2
(WaMu). In motion sequence 003, Plaintiff moves for an order granting it summary judgment on its complaint, striking Joshua's answer, appointing a referee to compute the sums due and owing to plaintiff, entering a default judgment against non-appearing defendants New York State Department of Taxation and Finance, New York City Environmental Control Board and New York City Department of Housing Preservation and Development and dismissing the complaint without prejudice as against de
fendants John DOE No.1 to John Doe No. XXX. In motion sequence 004, plaintiff moves, by Order to Show Cause (OSC), for the appointment of a temporary receiver. Joshua opposes these motions on the grounds that the plaintiff lacks standing to foreclose upon the mortgage and has failed to adequately demonstrate that Joshua is in default with respect to the Note.

BACKGROUND
On August 12, 2005, Joshua signed a promissory note and mortgage agreement in favor of WaMu in order to obtain a loan in the amount of $2,812,500.00. The loan was secured by property located at 2866 Frederick Douglass Boulevard, New York, New York. The mortgage was recorded with the Office of the City Register on August 26, 2005 (see Affirmation of Jerold C. Feuerstein, Esq. [Feuerstein Aff.], exhibits A, B).
On September 25, 2008, the United States Office of Thrift Supervision (OTS) seized WaMu and placed it into the receivership of the Federal Deposit Insurance Corporation (FDIC). That same day, the FDIC transferred and/or sold most of WaMu's assets, including its deposit liabilities and its secured debts and loans to JPMorgan Chase & Co. (Chase). Pursuant to 12 USC §1821(d)(2)(G)(i)(II), the FDIC, as receiver of a failed bank, is authorized to "transfer any asset or liability of the institution in default…without any approval, assignment, or consent with respect to such transfer." WaMu's loans were transferred to Chase through a Purchase of Assumption Agreement (the PAA) executed by FDIC and Chase on September 25, 2008 (id., exhibit C). As proof that the Note and mortgage executed by Joshua was one of the loans transferred to Chase, the plaintiff relies on an affidavit signed by Robert C. Schoppe (Schoppe
*3
Affidavit), an authorized representative of the FDIC. The Schoppe Affidavit claims that "Chase acquired certain of the assets, including all loans and all loan commitments, of Washington Mutual." However neither the Schoppe Affidavit nor the PAA mention or refer to any specific loans.
On August 19, 2011, the subject mortgage was assigned and the Note endorsed over to N.Y. Brooklyn Investor II, LLC, a New York limited liability company (NY Brooklyn Investor). On September 12, 2011, NY Brooklyn Investor assigned the mortgage and Note over to the plaintiff (id., exhibits D, E). Both of these assignments were registered and recorded on October 3, 2011 (id.).
Pursuant to the terms of the Promissary Note, Joshua was obligated to make monthly payments of $15,600.48, starting on October 1, 2005. Plaintiff claims that Joshua is in default because it failed to tender any monthly payments on the Note on or after December 1, 2010. The mortgage agreement provides that the mortgagors are in default when they fail to make any regular payment under the Note "so that it was received by the [lender] within 15 days after the date when due" (id., exhibit B). Section 5.3 of the Mortgage, provides in pertinent part, "Upon the occurrence of any Event of Default, all sums secured hereby shall become immediately due and payable, without notice or demand…and Lender may…(b) Foreclose this Security Instrument as provided in Section 7 or otherwise realize upon the Property…" (id.). By letter dated April 22, 2011, counsel for Chase informed Joshua that Chase was exercising its option to declare the entire principal amount of the loan in default, together with all accrued and unpaid interest and to commence a foreclosure proceeding against Joshua (id., exhibit G).
Prior to its assigning the mortgage and Note to NY Brooklyn Investor, Chase commenced this action to foreclose upon the property via a summons and complaint dated May 20, 2011. In addition to Joshua, Chase named various other parties with an interest in the property as well as defendants John Doe No.1 through John Does No. XXX, as potential tenants of or unknown creditors or lien holders on the property. On July 12, 2011, Joshua
*4
interposed an answer which, inter alia, raised seven affirmative defenses: (1) failure to state a cause of action; (2) unclean hands; (3) denial of default and, alternatively that default was "wrongfully induced by the Plaintiff; (4) denial of any non-monetary default; (5) failure to provide notice and a cure period; (6) reservation of the right to amend the answer to include new affirmative defenses; and (7) denial of waiver of affirmative defenses. On November 16, 2011, this Court signed an order amending the caption of this action to reflect the substitution of FTBK Investor II, LLC, as trustee for NY Brooklyn Investor II Trust I as the plaintiff in the action.
In motion sequence 003, plaintiff moves for an order granting summary judgment, striking Joshua's answer, and appointing a referee to compute the sums due and owing to Plaintiff. Joshua opposes this relief. Plaintiff also seeks an order dismissing the John Doe defendants without prejudice and entering a default judgment against defendants New York State Department of Taxation and Finance, New York City Environmental Control Board and New York City Department of Housing Preservation and Development, all of whom have failed to answer the complaint or otherwise appear in this action. Joshua does not offer any opposition to the granting of this relief. In motion sequence 004, Plaintiff moves, by OSC for the appointment of a temporary receiver for the property. Joshua opposes.

CONTENTIONS OF THE PARTIES
Plaintiff asserts that it is the valid holder of the Note and mortgage, signed by Joshua, that Joshua has failed to make the required payments pursuant to the Note and is therefore in default. As such, plaintiff proffers that it has established a prima facie case that it is entitled to foreclose on the property. Plaintiff also maintains that Joshua's answer does not raise any meritorious defenses that would negate the plaintiff's prima facie showing. In addition to producing the indorsed Note, the mortgage agreement, and the two mortgage assignments, plaintiff has also submitted an affidavit from Brian Shatz (Shatz), the managing member of the plaintiff trustee. Shatz states that he has personal knowledge of the existence of Joshua's default and the amount of the principal balance due "based upon Plaintiff's books and records"
*5
(Feuerstein Aff., Shatz Affid., ¶21). Shatz states in his affidavit that he reviewed files maintained in the ordinary course of business by plaintiff and Chase that relate to the loan that is the subject of this action.
Joshua contends that summary judgment should be denied because plaintiff has failed to provide any proof that the mortgage and note were transferred from the FDIC to Chase, plaintiff's predecessor-in-interest, and therefore plaintiff has failed to sufficiently demonstrate that it has standing to foreclose on the mortgage. Joshua further claims that plaintiff lacks standing because there is no endorsement or allonge on the Note evidencing its valid assignment to Chase. Furthermore, Joshua claims that Shatz's affidavit is insufficient proof of Joshua's default on the Note because he has not demonstrated sufficient personal knowledge of the circumstances surrounding Joshua's alleged default.

In reply, plaintiff claims that a formal assignment of the mortgage and note to Chase was not necessary to effectuate a transfer. Plaintiff also submits a Supplemental Affidavit from Shatz. In his Supplemental Affidavit, Shatz claims that he reviewed the files concerning the subject loan before plaintiff acquired the loan from NY Brooklyn Investor, including all loan related files such as the underwriting file, loan documents, payment histories, default and acceleration letters and other correspondences. Shatz indicates in the Supplemental Affidavit, that the documents he reviewed were presented to him as "business records of the predecessors in interest to NY Brooklyn (and Plaintiff for that matter) and they appeared to [him] to be consistent with similar business records customarily held in the mortgage lending industry" (Feuerstein Reply Aff., Shatz Sup. Affid. at p. 3).

With regards to the appointment of a temporary receiver, plaintiff relies on section 5.3 of the mortgage agreement which states that in the event of a default" Mortgagee may…[h]ave a receiver appointed as a matter of right on an ex parte basis without notice to Mortgagor and without regard to the sufficiency of the Property or any other security for the indebtedness secured hereby and, without the necessity of posting a bond or security, such receiver shall take
*6
possession and control of the Property and shall collect and receive all of the rents, issues and profits thereof" (Feuerstein Aff., exhibit B). Plaintiff contends that this provision, read in conjunction with Real Property §254(10), entitles it to have a receiver appointed for the Property regardless of the sufficiency of the current property management. Moreover, plaintiff asserts that Joshua has failed to properly manage the subject property. Joshua again contends that plaintiff provides insufficient proof that it is the valid holder of the note and mortgage. Joshua also disputes plaintiff's contentions that it is not managing the property effectively, and argues that the appointment of a receiver could disrupt its management and is otherwise not necessary to protect the plaintiff's collateral.

STANDARD
Summary judgment is a drastic remedy that should be granted only if no triable issues of fact exist and the movant is entitled to judgment as a matter of law (see Alvarez v. Prospect Hosp., 68 NY2d 320, 324 [1986]; Andre v. Pomeroy, 35 NY2d 361, 364 [1974]). The party moving for summary judgment must make a prima facie showing of entitlement to judgment as a matter of law, tendering sufficient evidence in admissible form demonstrating the absence of material issues of fact (see Winegrad v. New York Univ. Med. Ctr., 64 NY2d 851, 853 [1985]; CPLR 3212[b]). A failure to make such a showing requires denial of the motion, regardless of the sufficiency of the opposing papers (see Smalls v. AJI Indus. Inc., 10 NY3d 733, 735 [2008]). Once a prima facie showing has been made, however, "the burden shifts to the nonmoving party to produce evidentiary proof in admissible form sufficient to establish the existence of material issues of fact that require a trial for resolution" (Giuffrida v. Citibank Corp., 100 NY2d 72, 81 [2003]; see also Zuckerman v. City of New York, 49 NY2d 557, 562 [1980]; CPLR 3212[b]).
When deciding a summary judgment motion, the Court's role is solely to determine if any triable issues exist, not to determine the merits of any such issues (see Sillman v. Twentieth Century-Fox Film Corp., 3 NY2d 395, 404 [1957]). The Court views the evidence in the light most favorable to the nonmoving party, and gives the nonmoving party the benefit of all
*7
reasonable inferences that can be drawn from the evidence (see Negri v. Stop & Shop, Inc., 65 NY2d 625, 626 [1985]). If there is any doubt as to the existence of a triable issue, summary judgment should be denied (see Rotuba Extruders, Inc. v. Ceppos, 46 NY2d 223, 231 [1978]).
In moving for summary judgment in a mortgage foreclosure action, plaintiff establishes a prima facie right to foreclose by producing the mortgage, the assignment, if any, the unpaid note and evidence of default (see CitiFinancial Co. (DE) v. McKinney, 27 AD3d 224, 226 [1st Dept 2006]; LPP Mortgage, Ltd v. Card Corp., 17 AD3d 103, 104 [1st Dept 2005]; Hypo Holdings, Inc. v. Chalasani, 280 AD2d 386 [1st Dept 2001]). Once the plaintiff satisfies that burden, it is incumbent on the party opposing foreclosure to come forward with evidence sufficient to raise a triable issue of fact as to a bona fide defense such as waiver, estoppel, bad faith, fraud, or oppressive or unconscionable conduct on the part of the plaintiff (see CitiFinancial, 27 AD3d at 226; Mahopac Nat. Bank v. Baisely, 244 AD2d 466, 467 [2nd Dept 1997]). Where the defendant has put standing into issue, the plaintiff can demonstrate its standing and entitlement to relief by demonstrating that it is both the holder or assignee of the subject mortgage and the holder or assignee of the underlying note at the time the action is commenced (see U.S. Bank, N.A. v. Collymore, 68 AD3d 752, 753 [2nd Dept 2009]; see also Bank of New York v. Silverberg, 86 AD3d 274, 279 [2nd Dept 2011]; Countrywide Home Loans, Inc. v. Gress, 68 Ad3d 709, 709 [2nd Dept 2009]).

DISCUSSION
Usually, an assignment of a mortgage and underlying note can be effectuated either through a written assignment of the underlying note or the physical delivery of the note prior to the commencement of the foreclosure action (Collymore, 68 AD3d at 754). Joshua argues that the plaintiff cannot establish that it has standing because it cannot demonstrate that the mortgage and underlying note was validly assigned to Chase, plaintiff's predecessor-in-interest, prior to the commencement of this action. Plaintiff has provided a written assignment of both the mortgage and the underlying Note from Chase to NY Brooklyn Investor and from NY
*8
Brooklyn Investor to plaintiff. However, plaintiff does not have written proof of the assignment to Chase from either WaMu or the FDIC, as receiver. The only proof that plaintiff has offered regarding the transfer of the subject loan from WaMu to the FDIC and/or Chase is the affidavit by Schoppe, the FDIC representative. As stated above, the Schoppe affidavit does not refer to any specific loans or mortgages but merely asserts that all of WaMu's loans were transferred to Chase after WaMu's seizure by the FDIC.
Joshua acknowledges that the plaintiff is in physical possession of the note and mortgage, but argues that the motion must be denied because the plaintiff has not provided any admissible evidence such as an affidavit or documents which would demonstrate that the loan documents were delivered to Chase prior to the commencement of this action. Plaintiff may have demonstrated that it was validly assigned the loan from Chase and NY Brooklyn Investor, but Joshua insists that plaintiff must also demonstrate that Chase was validly assigned the note and mortgage from WaMu and/or the FDIC as receiver prior to the commencement of this action.

Based on the above facts, Joshua argues that the evidence proffered by the plaintiff to demonstrate its standing is insufficient. The Court disagrees. Plaintiff correctly points out that the FDIC clearly had the authority to transfer the loans in bulk to Chase pursuant to 12 USC §1821 (d)(2)(G)(i)(II), and that an individual negotiation, i.e. assignment, of each loan was not required. Pursuant to 12 USC §1821 (d)(2)(G)(i)(II), the FDIC, as receiver of a failed bank, is authorized to "transfer any asset or liability of the institution in default…without any approval, assignment, or consent with respect to such transfer." According to the express terms of the statute, a valid transfer of the assets of a failed bank from the FDIC occurs even without a formal assignment instrument. As evidenced by the terms of the PAA, Chase acquired all assets of WaMu, with certain exceptions not applicable to this action. Specifically, section 3.1 of the PAA provides that, with the exception of the assets not applicable to this action, "[Chase] hereby purchases from the receiver [FDIC], and the Receiver hereby sells, assigns, transfers,
*9
conveys, and delivers to the Assuming Institution, all right, title, and interest of the Receiver in and to all of the assets…of the Failed Bank [WaMu]" (Reply papers).
Citing to JP Morgan Chase Bank, N.A. v. 334 Marcus Garvey Boulevard Corp. (Sup Ct, Kings County, Dec. 5, 2011, Rosenberg, J., index No. 26152/09) and JP Morgan Chase Bank, N.A. v. 1770 Realty Corp. (Sup Ct, Kings County, Jan. 29, 2010, Gerges, J., index No.7655/09), plaintiff argues that it can therefore prove Chase's prior ownership of notes and mortgages obtained from WaMu without having to show that the loan documents were individually negotiated and assigned. The Court agrees with plaintiff. There is sufficient documentation to establish that OTS closed WaMu on September 25, 2008 and appointed the FDIC as WaMu's receiver. That same day, the FDIC transferred the bulk of WaMu's assets to Chase pursuant to the PAA. Joshua does not challenge the legality of the transfer or the PAA itself and indeed numerous courts have accepted these transactions as legitimate conveyances of WaMu assets to Chase (see 290 at 71 v. JP Morgan Chase Bank, 2009 WL 3784347, Case No A-09-CA=576-SS[WD Texas 2009] [finding that PAA validly transferred lease from WaMu to Chase]; Grealish v. WaMu, FA, 2009 WL 2170044, Case No 2:08-CV-763 TS [D Utah 2009]; Hilton v. Washington Mut. Bank, 2009 WL 3485953, No C09-1191 SI [ND Cal 2009]). Accordingly, Joshua's claim that the Note had to have been individually negotiated and physically endorsed to Chase through an allonge is legally incorrect.
Joshua argues that even if plaintiff is correct that Chase received a valid transfer of WaMu's assets from the FDIC, this does not rule out the possibility that the mortgage could have been transferred to another lender prior to WaMu's seizure by the FDIC. Thus Joshua argues that plaintiff must provide proof of Chase's prior ownership of the Note and mortgage beyond the PAA and/or the Schoppe affidavit. There is some caselaw supporting Joshua's position, but the Court does not find it persuasive (see FTBK Investor II LLC v. Mercy Holding LLC, 36 Misc3d 1219(A) *5 [Sup Ct. Kings County 2012]). In making this argument based on its analysis of state law, Joshua overlooks the broad powers granted to OTS which enjoys "plenary and exclusive authority…to regulate all aspects of the operations of Federal savings associations" and its authority "occupies the entire field of lending regulation for federal savings associations" (see 12 CFR §§545.2, 560.2[a]). To this end, OTS Regulation 560.2(b) expressly preempts state regulation of federal thrift activities dealing with lending by federal savings associations including, inter alia, terms of credit, loan related fees, disclosure or advertising and processing, origination or servicing of loans (see 12 CFR §560.2(b); see also Monroig v. Washington Mut. Bank, FA, 19 AD3d 563, 564 [2nd Dept 2005]). There can be no dispute that 12 USC §1821 (d)(2)(G)(i)(II), as it pertains to the broad authority of the OTS and FDIC to transfer mortgages without assignment, pertains to lending, and thus any contrary New York state law or judicial decision would be preempted by federal law (see JP Morgan Chase Bank, N.A. v. 1770 Realty Corp., Sup Ct, Kings County, Jan. 29, 2010, Gerges, J., index No.7655/09, slip op at 16-18; JP Morgan Chase Bank, N.A. v. 334 Marcus Garvey Boulevard Corp., Sup Ct, Kings County, Dec. 5, 2011, Rosenberg, J., index No. 26152/09, slip op at 7-8). Thus, the Court finds that Joshua's contention that the transfer of the mortgage and Note to Chase must be negotiated and/or recorded individually to demonstrate proof of assignment is without merit.

Furthermore, as plaintiff points out, while Joshua argues that the plaintiff has failed to prove valid ownership of the subject loan documents, Joshua fails to give any rational explanation as to how Chase and then the plaintiff obtained possession of the loan documents if in fact WaMu transferred the loan prior to its collapse as Joshua suggests. Faced with plaintiff's strong prima facie showing as to ownership, Joshua cannot point to any credible evidence which suggests that the underlying note was not assigned to Chase from the FDIC and thereafter, from Chase to NY Brooklyn Investor, and then to plaintiff.
However, Joshua also claims that plaintiff has failed to provide sufficient documentary evidence of Joshua's alleged default on payment of the note, arguing that the Shatz affidavit is insufficient to demonstrate default because Shatz had no involvement with the loan and mortgage at the time of the purported default, and thus lacks sufficient personal knowledge of
*11
the circumstances concerning Joshua's alleged default. In his original affidavit, Shatz says only that he reviewed the files of the plaintiff and Chase, as plaintiff's predecessor-in-interest and knows that the allegations in the complaint concerning Joshua's default are true based on his review of the plaintiff's books and records (see Shatz Affidavit). As a member of the plaintiff assignee, Shatz only reviewed the loan documents created by Chase long after the alleged default took place and has no personal knowledge of the circumstances surrounding the default and or the acceleration of the mortgage by Chase. Furthermore Shatz can not represent that the records that he reviewed were kept by Chase in the ordinary course of business and his affidavit does not even specify or attach copies of the documents upon which he relies (see FBTK Investor II, 2012 WL 3064864 at *5). Even if the documents were attached, they would not be admissible as business records of Chase without an affidavit of a Chase employee indicating that such records were kept in the regular course of Chase's business (see CPLR 4518[a]; Lodato v. Greyhawk N.Am., LLC, 39 AD3d 494, 495 [2nd Dept 2007]). Moreover, Shatz lacks personal knowledge of the facts of the subject mortgage and note prior to its transfer to NY Brooklyn Investor. While the supplemental affidavit of Shatz attempts to cure some of the deficiencies, it is still inadequate and a party can not be permitted to make out his prima facie case on reply (see Cotter v. Brookhaven Mem. Hosp. Med. Ct., Inc., 97 AD3d 524 [2d Dept 2012]; Hawthorne v. City of New York, 44 AD3d 544 [1st Dept 2007]). Therefore, plaintiff cannot meet its burden to demonstrate that Joshua defaulted on the note, and accordingly its motion for summary judgment should be denied without prejudice with leave to renew. Plaintiff's motion seeking an order dismissing the John Doe defendants without prejudice and entering a default judgment against defendants New York State Department of Taxation and Finance, New York City Environmental Control Board and New York City Department of Housing Preservation and Development is granted without opposition.
In motion sequence 004, plaintiff moves for the appointment of a temporary receiver pursuant to section 5.3(a) of the mortgage agreement and Real Property Law 254(10). Since
*12
the language in the mortgage agreement allowing for the appointment of a receiver without regard to the sufficiency of the property is contingent upon proof of default, and plaintiff has not yet demonstrated that Joshua defaulted on the mortgage, the application for appointment of a temporary receiver is also denied without prejudice with leave to renew.

CONCLUSION
Accordingly, it is
ORDERED that the portions of plaintiff's motion in Motion Sequence 003 seeking summary judgment on its complaint, striking defendant Joshua's answer, and seeking the appoint a referee to compute sums due and owing to plaintiff are denied without prejudice with leave to renew; and it is further,
ORDERED that the portion of plaintiff's motion in Motion sequence 003 seeking to dismiss the complaint without prejudice as against defendants John Doe No.1 to John Doe No. XXX is granted without opposition; and it is further,
ORDERED that the portion of plaintiff's motion in Motion Sequence 003 seeking a default judgment as against defendants New York State Department of Taxation and Finance, New York City Environmental Control Board and New York City Department of Housing Preservation and Development is granted without opposition; and it is further,
ORDERED that Motion Sequence 004 is denied in its entirety without prejudice with leave to renew; and it is further,
ORDERED that counsel for plaintiff is directed to serve a copy of this Order with Notice of Entry upon all parties and upon the Clerk of the Court who is directed to enter judgment accordingly; and it is further,
ORDERED that the parties are directed to appear for a Status Conference on March 13, 2013 at 11:00 a.m., at 60 Centre Street, Room 341, Part 7.